| Consensus | Consensus Range | Actual | Previous | Revised | |
| Annual Rate | 620K | 606K to 647K | 607K | 628K | 678K |
Highlights
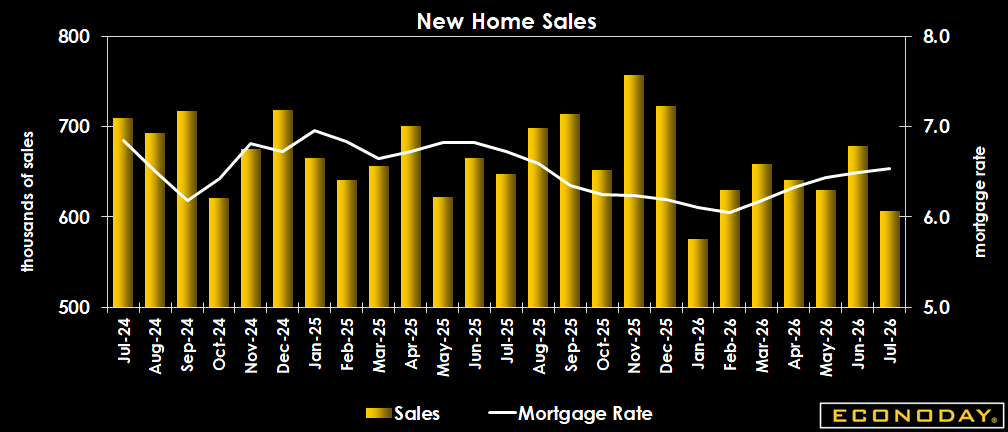
Against the backdrop of higher mortgage rates, the housing market showed signs of weakening in July, following a rebound in June. U.S. new home sales fell more than expected on the month, to an annual rate of 607,000 in July, below the consensus expectation of 620,000 in an Econoday survey of forecasters. The 10.5 percent monthly drop was only partly offset by an upward revision to June’s estimate to 678,000 from 628,000.
The annual rate was down 6.3 percent from July 2025.
Regionally, declines of 42.7 percent in the Midwest and 13.0 percent in the South outpaced increases of 30.3 percent in the Northeast and 6.2 percent in the West.
Annualized estimates show that of the 607,000 new home sales, an estimated 343,000 were not completed,193,000 were under construction, and 71,000 had yet to be started.
The median sales price of new houses sold in July was $393,800, down 2.3 percent from June and 0.9 percent from a year earlier. It remains to be seen how the escalation of the trade war between Canada and the U.S. will impact the supply chain and housing prices, especially construction costs, while higher mortgages are likely to weigh on demand. “Building material tariffs heighten market uncertainty, strain supply chains and increase construction costs,” the NAHB said Monday.
The inventory of new houses for sale rose 1.9 percent from June to 488,000 in July, representing 9.6 months at the current sales pace, up from 8.5 months in June.
Market Consensus Before Announcement
Sales seen receding to 620K rate in July after rising to 628K in June as housing remains in doldrums.
Definition
New home sales measure the number of newly constructed homes with a committed sale during the month. The level of new home sales indicates housing market trends and, in turn, economic momentum and consumer purchases of furniture and appliances.
Description
This provides a gauge of not only the demand for housing, but the economic momentum. People have to be feeling pretty comfortable and confident in their own financial position to buy a house. Furthermore, this narrow piece of data has a powerful multiplier effect through the economy, and therefore across the markets and your investments. By tracking economic data such as new home sales, investors can gain specific investment ideas as well as broad guidance for managing a portfolio. Each time the construction of a new home begins, it translates to more construction jobs, and income which will be pumped back into the economy. Once the home is sold, it generates revenues for the home builder and the realtor. It brings a myriad of consumption opportunities for the buyer. Refrigerators, washers, dryers and furniture are just a few items new home buyers might purchase. The economic"ripple effect" can be substantial especially when you think a hundred thousand new households around the country are doing this every month. Since the economic backdrop is the most pervasive influence on financial markets, new home sales have a direct bearing on stocks, bonds and commodities. In a more specific sense, trends in the new home sales data carry valuable clues for the stocks of home builders, mortgage lenders and home furnishings companies.