| Consensus | Consensus Range | Actual | Previous | |
| Index | 47.8 | 45.5 to 48.5 | 48.1 | 47.8 |
| Year-ahead Inflation Expectations | 4.6% | 4.6% to 4.6% | 4.6% | 4.6% |
| Index Change | 0.3 | -3.9 | ||
| Index % Change | 0.6% | -7.5% |
Highlights
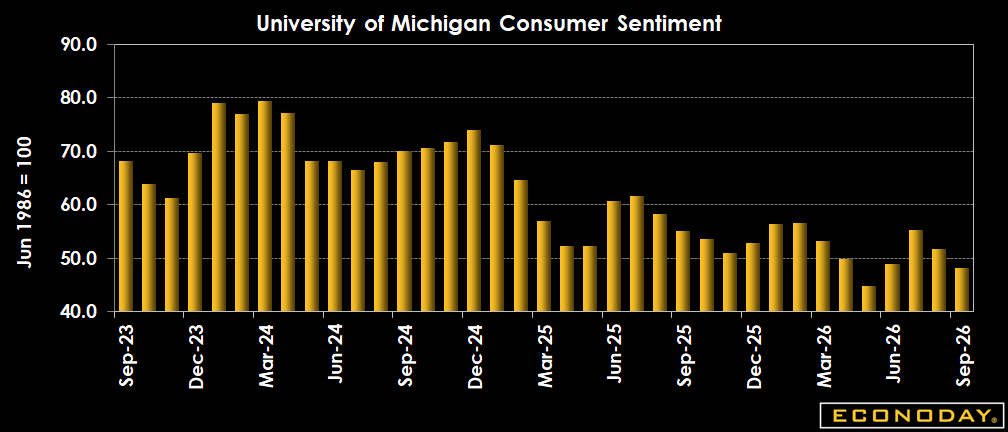
U.S. consumer sentiment took another step back this month, with September’s final reading coming in at 48.1 vs. 51.7 in August and 55.2 in July. This is above the consensus of 47.8 in the Econoday survey of forecasters. Consumer sentiment fell 7.0 percent, dragged down by inflation worries, financial concerns, and the renewed trade hostilities with Canada.
Sentiment is down 12.7 percent from September 2025 as year-ahead expectations for both personal finances and business conditions plunged.
“Views of current and year-ahead expected personal finances both weakened about 10 percent this month, with concerns over high prices continuing to climb,” the report said.
Inflation fears are also pulling demand forward, with an uptick in durable goods purchases due in part to the belief that prices will be higher in the future.
“The short-run outlook for business conditions plunged amid renewed worries that elevated fuel prices and re-escalating trade disputes could pass through to the economy as a whole,” the report added.
Final year-ahead inflation expectations jumped to 4.6 percent in September from 4.0 percent in August. This significantly exceeds the 3.4 percent reading seen in February before the Iran conflict began, along with all 2024 readings, the report said.
Long-run inflation expectations in September rose to 3.4 percent from 3.3 percent last month, staying above the 2.8 percent to 3.2 percent range seen in 2024.
Market Consensus Before Announcement
The consensus sees no revision in sentiment for the final September report from 47.8 in the flash. One-year inflation expectation also expected unrevised at 4.6 percent.
Definition
The University of Michigan's Consumer Survey Center questions households each month on their assessment of current conditions and expectations of future conditions. Preliminary estimates for a month are released at mid-month and are based on about 420 respondents. Final estimates are released near the end of the month and are based on about 600 respondents.
Description
The pattern in consumer attitudes and spending is often the foremost influence on stock and bond markets. For stocks, strong economic growth translates to healthy corporate profits and higher stock prices. For bonds, the focus is whether economic growth goes overboard and leads to inflation. Ideally, the economy walks that fine line between strong growth and excessive (inflationary) growth.
This balance was achieved through much of the nineties and, in large part because of this, investors in the stock and bond markets enjoyed huge gains. It was during the late nineties that the consumer sentiment index hit its historic peak, reaching levels that were never matched during the subsequent 2001 to 2007 expansion nor during the long expansion following the Great Recession.
Consumer spending accounts for more than two-thirds of the economy, so the markets are always dying to know what consumers are up to and how they might behave in the near future. The more confident consumers are about the economy and their own personal finances, the more likely they are to spend. With this in mind, it's easy to see how this index of consumer attitudes gives insight to the direction of the economy. Just note that changes in consumer confidence and retail sales don't move in tandem month by month.